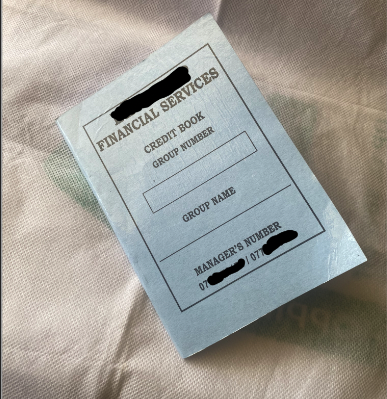
Small and medium enterprises (SMEs), SACCOs and membership clubs are the backbone of Uganda’s economy, yet their financial records often live in paper ledgers and passbooks. Transactions are typically routed through mobile money networks dominated by MTN and Airtel, which levy high fees and limit flexibility. Cross‑border trade within the East African Community (EAC) is further hampered by currency conversion costs and lack of integrated payment systems.
Digital finance across Africa is already transforming access to money. Mobile money and agent banking provide affordable, instant transactions, savings, credit and even insurance to millions of people, including those in rural areas. These innovations show that technology can deliver convenience and financial inclusion at scale. By moving away from paper and manual processes, communities gain faster services and better transparency.
The EAC recognises this potential. In 2025 the bloc approved a Cross‑border Payment System Masterplan aimed at creating an integrated payments environment. The plan seeks to lower the cost and time of cross‑border transactions, promote the use of local currencies, deepen financial markets and support digital inclusion across member states. Such reforms will make it easier for Ugandan cooperatives and SMEs to trade with their neighbours.
Within cooperatives, digital platforms like Wakandi’s SACCO system illustrate how technology can simplify operations. Wakandi automates tasks such as member onboarding, loan approvals and record keeping, giving members convenient online access while improving transparency and accountability. This kind of digital infrastructure lays the foundation for more advanced services.
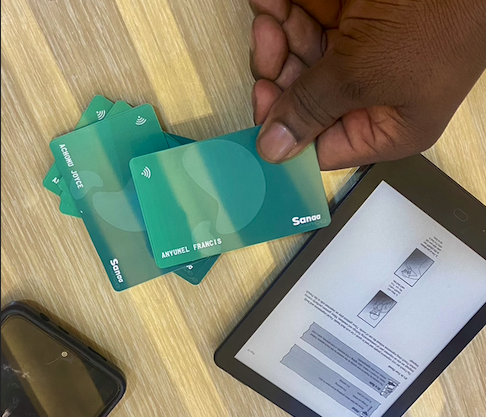
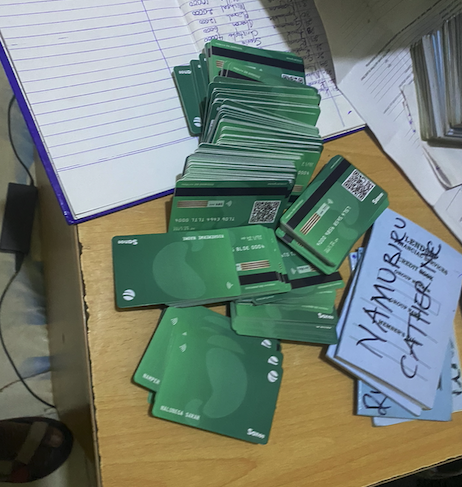
Sanaa Smart Cards build on these trends by offering a card‑based account designed specifically for SACCOs, membership clubs and SMEs. Think of them as a Visa‑style card tailored for local cooperatives. Each card links to a Sanaa OS digital account, allowing members to receive contributions, make purchases, transfer funds and manage credit without relying on bulky ledger books. Transactions are recorded instantly, providing real‑time visibility and reducing the risk of fraud.
Imagine a coffee farmers’ SACCO whose members receive a Sanaa card. A member can buy fertilizers or equipment from a business that accepts Sanaa cards, and the payment settles immediately through the Sanaa network without passing through MTN or Airtel. Farmers can also use their cards in Soko 24 to order supplies or sell produce on credit. Smart contracts on Sanaa OS automate repayment schedules, enabling buy‑now‑pay‑later financing for inputs while ensuring repayment terms are enforced.
Sanaa Smart Cards align with the EAC’s vision of a digital single market. By facilitating cross‑border acceptance and reducing dependency on specific telecom networks, they help cooperatives and SMEs trade across Uganda, Kenya, Tanzania, Rwanda and beyond. The cards integrate seamlessly with Sanaa Media for marketing and education and with Soko 24 for market sourcing and distribution. This holistic ecosystem empowers local businesses to reach new customers, share information effortlessly and participate fully in the emerging digital economy.
By adopting Sanaa Smart Cards, SACCOs and membership clubs can leap from paper and monopoly‑bound systems into a transparent, efficient and borderless financial future. The combination of secure digital accounts, smart contracts and integrated marketplaces will bring our people closer together, amplify trade within the EAC and unlock new opportunities for inclusive growth.
Sanaa Smart Cards: Revolutionising SME Finance and Cross-Border Trade in the EAC
Comments
0Be the first to comment.